All Categories
Featured
Table of Contents
Providing consumers with services is why they are still in organization. Most of the companies involved in debt combination are certified by the Better Service Bureau and have A-plus ratings.
Ensure the company you choose has actually been certified by the American Fair Credit Council or the International Association of Specialist Financial Obligation Arbitrators. These companies guarantee companies follow standards to safeguard customers from unfair lending practices or fraud. A neglected but vital part of selecting a debt consolidation business is the instructional element.
The Internal revenue service needs nonprofits to supply an educational facet to their service to retain tax-exempt status as 501(c)( 3) companies., almost always at no cost.
Comparing the Top Debt Relief Options
Contact the National Federation for Credit Therapy (NFCC) if you have questions on certification. Be careful of the typical red flags customers deal with when consolidating debt.
Seeking charges for services before reaching a composed contract with your financial institutions. Using aggressive sales pitches, asking you to act quickly on a choice that requires research and time. Promising a "fast repair" option. All financial obligation relief programs take some time, the majority of them in between 3 and 5 years. Be suspicious of companies assuring faster results.
Smart Tips to Manage 2026 Financial HardshipSuppose you have enough earnings to pay down financial obligation but need a customized program or kind of instructions to get started. A financial obligation management program may be better than a debt combination loan or debt settlement.
Understand the advantages of the service you choose. It is very important to find a program that offers the kind of debt consolidation you desire, makes you feel comfy dealing with their personnel and requirements, and educates you while you're in the program to restrict future obstacles. Debt debt consolidation programs can eliminate debt in 3-to-5 years.
The Step-By-Step 2026 Financial Hardship Guide
You likely didn't get into financial obligation in a hurry. Focus on making good spending options and on-time financial obligation payments. Eliminating financial obligation is a worthwhile challenge.
Debt combination works for consumers with stable incomes, typically no matter credit report, but not everybody will qualify. Some may not make sufficient to cover the monthly payments, while others may find alternative options to work much better for their unique situation. Credit counselors can inform you of your choices and let you know whether financial obligation combination is in your finest interest.
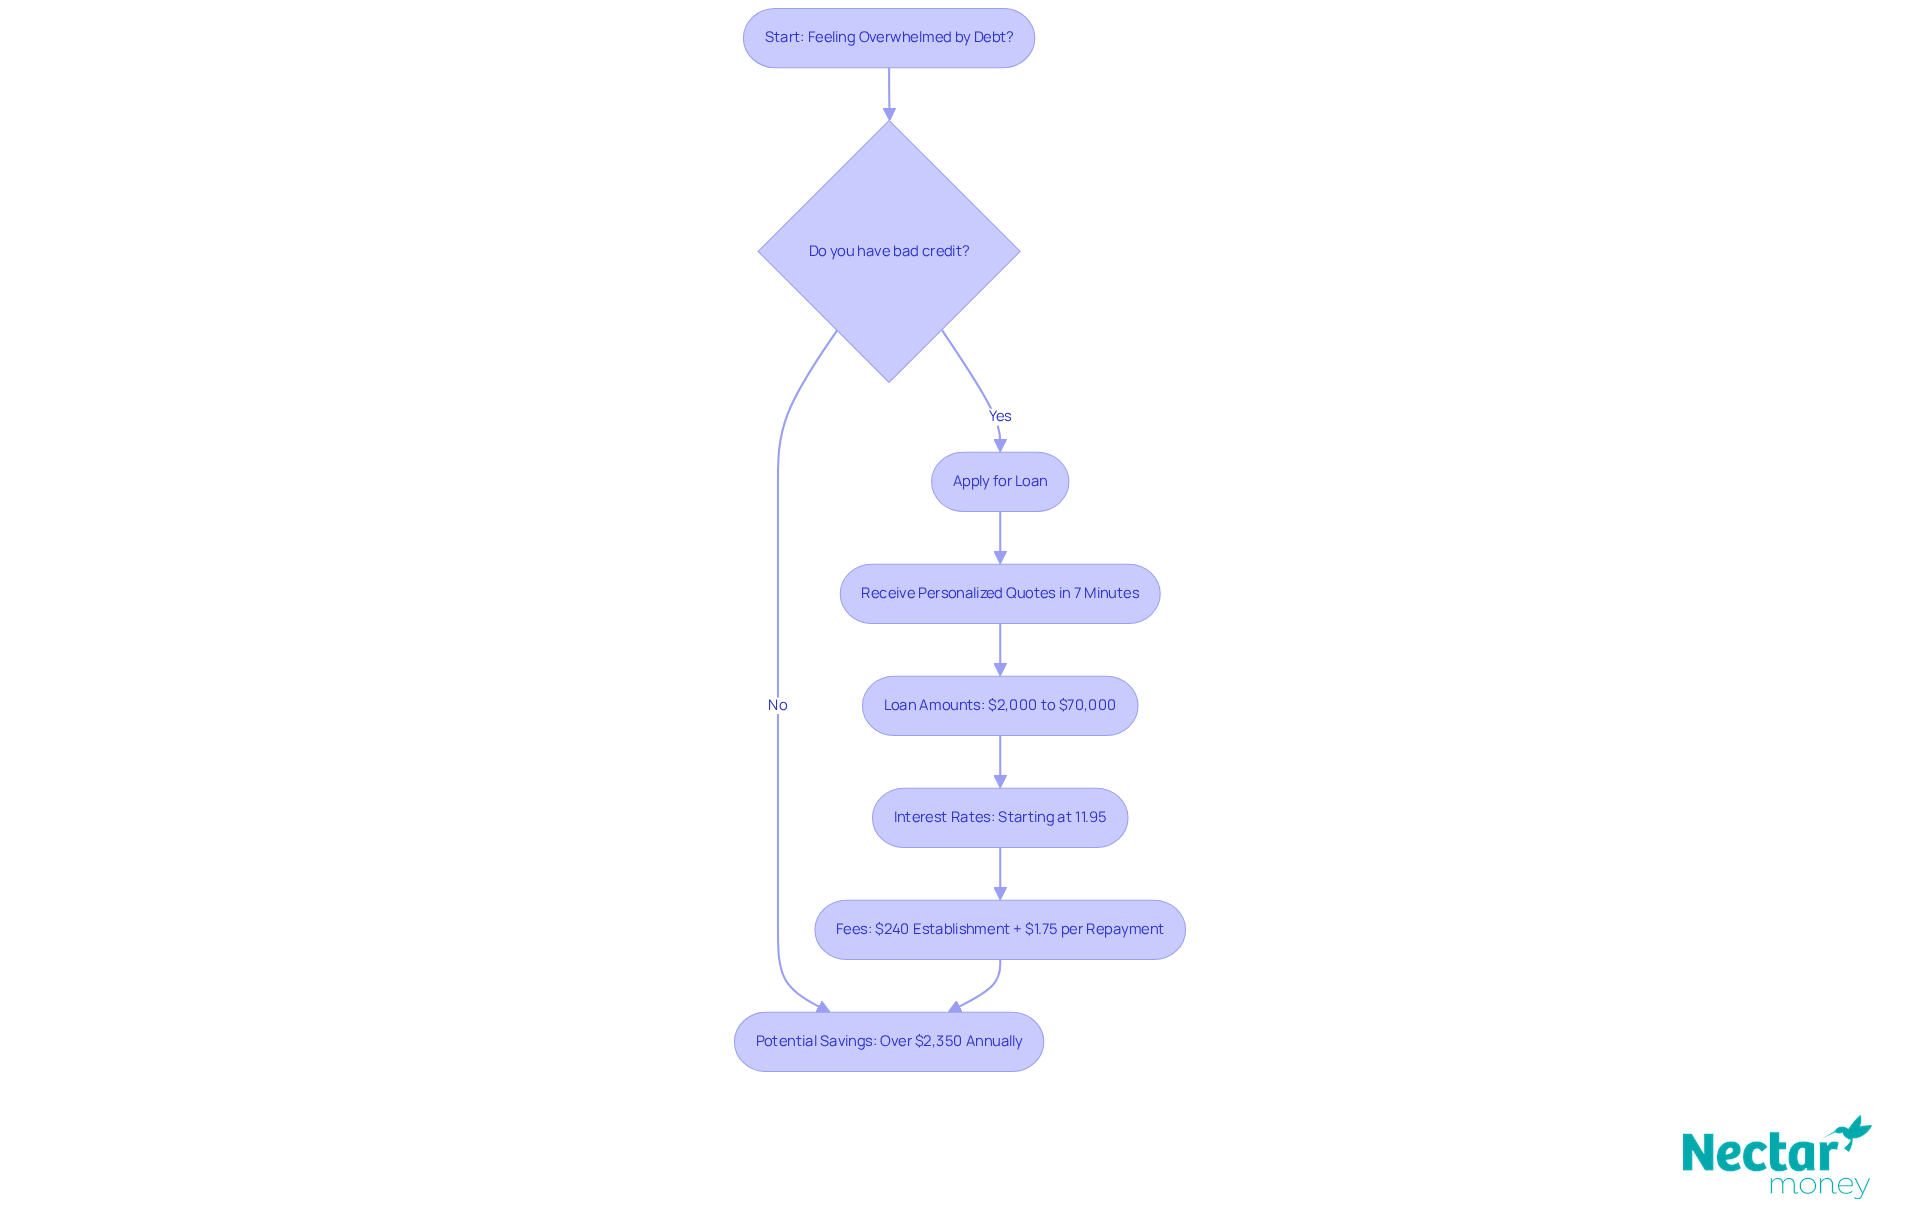
Credit therapy is a complimentary or affordable service provided by financial obligation consolidation business. Counselors will evaluate your credit report while building a budget that works to stabilize your earnings and expenses. They might recommend enrolling in a debt management program or taking part in real estate or bankruptcy therapy. It's absurd to tackle your financial obligation without a strategy.
Lots of consumers will find offers for 0% interest in between 12-18 months.
Expert Insights Into New Credit Relief Strategies
Be conscious of transfer charges typically balancing 2% to 3% of the debt transferred. If you're a house owner, consider a home equity loan or home equity line of credit.

The timing of offered funds upon loan approval might differ depending upon your bank's policies. Loan amounts range from $2,000$50,000. Citizens of Massachusetts have a minimum loan amount of $6,500; Ohio, $5,001; and Georgia, $3,001.

Latest Posts
Actionable Tips to Reduce High-Interest Liabilities in 2026
Critical Analysis Into New Credit Relief Trends
Expert Insights Into 2026 Debt Consolidation Strategies